


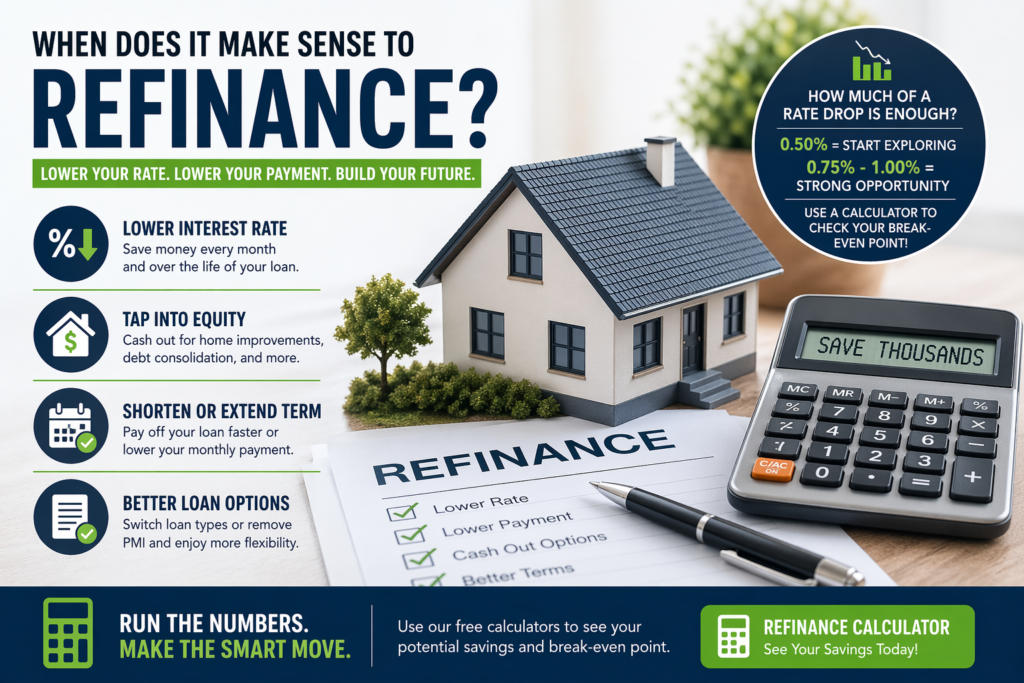
Refinancing can be one of the most powerful financial moves a homeowner makes—but timing is everything. With interest rates constantly shifting, many homeowners ask the same question: “How much do rates need to drop before refinancing makes sense?”
The Rate Drop Rule: How Much Is Enough?
A common rule of thumb is a 0.5% to 1% drop in interest rate before refinancing. But that’s only part of the story.
When Refinancing Usually Makes Sense:
- 0.50% drop → Worth exploring (especially on larger loan balances)
- 0.75%–1.00% drop → Strong refinance opportunity
- Less than 0.50% → May still work if you’re removing PMI, switching loan types, or consolidating debt
👉 The real key is your break-even point—how long it takes for your monthly savings to cover closing costs.
Use this tool to calculate it:
🔗 Refinance Calculator
Break-Even Point: The Decision Maker
If refinancing costs you $4,000 and saves you $200/month:
- Break-even = 20 months
- If you plan to stay longer than that → ✔️ refinance makes sense
- If not → ❌ reconsider
Top Reasons to Refinance (Beyond Rates)
Refinancing isn’t just about chasing lower rates. Here are smart scenarios where it makes sense:
- Lower your monthly payment
- Remove mortgage insurance (PMI)
- Switch from FHA to Conventional
- Tap into home equity (cash-out)
- Consolidate high-interest debt
- Change loan term (shorter or longer)
📖 Related:
🔗 Lower Your Payment or Cash Out Your Equity 💰🏡
Types of Refinancing Options (Pros & Cons)
1. Rate-and-Term Refinance
Best for: Lowering rate or changing loan term
Pros:
- Lower monthly payment
- Save thousands in interest
- No need to pull cash out
Cons:
- Closing costs apply
- Restarts loan timeline (in some cases)
2. Cash-Out Refinance
Best for: Accessing equity for large expenses
Pros:
- Lump sum cash
- Lower interest than credit cards
- Can fund renovations or investments
Cons:
- Increases loan balance
- Higher monthly payment possible
3. FHA Streamline Refinance
Best for: Existing FHA borrowers
Pros:
- Minimal documentation
- No appraisal (in most cases)
- Fast approval
Cons:
- Mortgage insurance remains
- Only for FHA loans
📖 Learn more:
🔗 Understanding FHA Streamline Refinance
4. VA IRRRL (Streamline for VA Loans)
Best for: Veterans lowering rates
Pros:
- No appraisal
- Minimal paperwork
- Lower costs
Cons:
- Only for VA loans
- Limited flexibility
5. HELOC (Alternative to Refinancing)
Best for: Keeping your current low rate
Pros:
- Access equity without refinancing first mortgage
- Flexible draw period
- Pay interest only on what you use
Cons:
- Variable interest rates
- Second lien on property
🔗 HELOC Calculator
📖 Bank Statement HELOC Guide
Should You Refinance in Today’s Market?
With shifting market conditions, the best move depends on your current rate, loan size, and goals.
📊 Stay informed:
🔗 Mortgage Rates & Market Trends
Pro Tip: Don’t Wait Too Long
Many homeowners try to “time the bottom” of interest rates—but that can backfire.
If refinancing:
- Saves you money today
- Fits your long-term plans
- Has a reasonable break-even
👉 It may already be the right time.
Tools to Help You Decide
Take control of your numbers with these calculators:
- 🔗 Mortgage Calculator
- 🔗 Affordability Calculator
- 🔗 Mortgage Qualification Calculator
- 🔗 Rent vs Buy Calculator
- 🔗 ARM Calculator
- 🔗 DSCR Calculator
Final Thoughts: Is Now the Time to Refinance?
Refinancing is not a one-size-fits-all decision. The right move depends on:
- Your current interest rate
- Your financial goals
- How long you plan to stay in the home
- The cost vs savings analysis
If the numbers make sense—even before a full 1% drop—it could be worth moving forward.
Ready to Explore Your Options?
📅 Book a personalized refinance strategy session:
👉 Schedule Your Appointment