


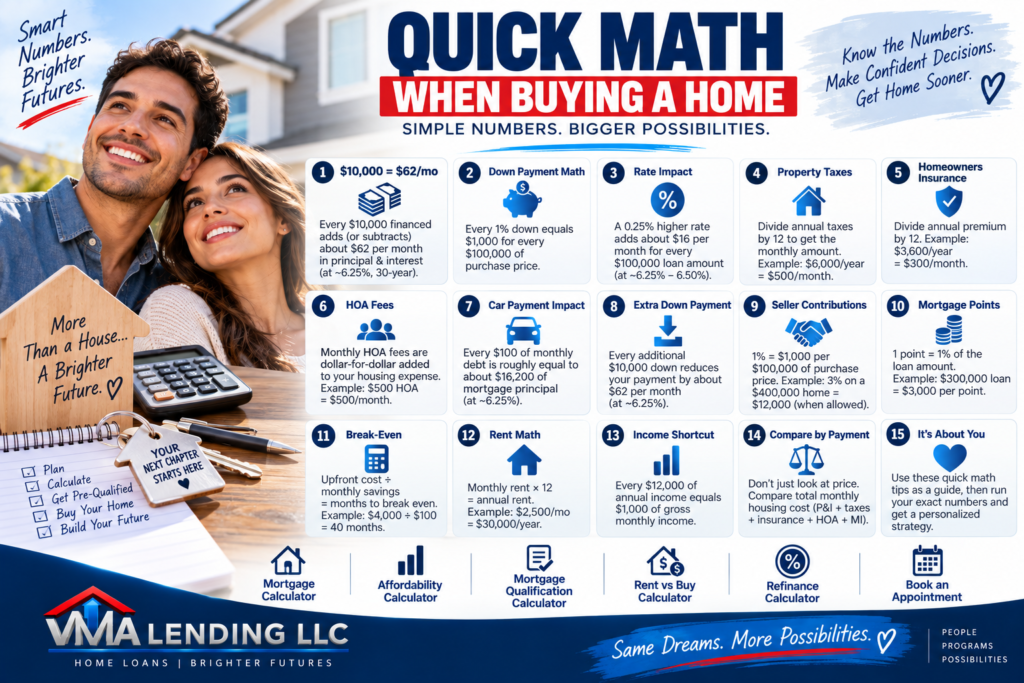
Buying a home can feel complicated because there are a lot of numbers flying around at the same time: purchase price, interest rate, down payment, taxes, insurance, HOA fees, closing costs and monthly payment.
But you don’t need a mortgage calculator open every second you’re looking at houses.
There are a few pieces of quick mortgage math that can help you look at a listing and almost immediately understand what changing one number could mean to your budget.
Think of these as shortcuts—not replacements for an actual Loan Estimate or mortgage qualification.
The Big One: Every $10,000 Financed Is About $62 Per Month
Here’s one of my favorite rules of thumb.
Using a 30-year fixed mortgage at approximately 6.25%, every additional $10,000 financed adds approximately:
$62 per month
That’s principal and interest only.
So if you’re comparing two homes and one costs $20,000 more, you don’t necessarily need to think:
“Wow, that’s another $20,000!”
Think:
About $123 more per month in principal and interest.
At the same approximate rate:
| Additional Amount Financed | Approx. Monthly P&I |
|---|---|
| $10,000 | $62 |
| $20,000 | $123 |
| $25,000 | $154 |
| $50,000 | $308 |
| $75,000 | $462 |
| $100,000 | $616 |
That can completely change how you look at houses.
Maybe you’re choosing between a $390,000 home and a $410,000 home.
The second house has the better neighborhood, extra bedroom, larger backyard and renovated kitchen.
The difference isn’t simply:
“It’s $20,000 more.”
The better question might be:
“Are those things worth approximately $123 more per month to me?”
Now you’re comparing something you can actually relate to your monthly budget.
You can run the exact numbers anytime with my Mortgage Calculator.
Important: The $62 shortcut assumes approximately 6.25% for 30 years and that the entire additional $10,000 is financed. If you’re making a down payment, the actual additional loan amount may be less. Rates also change, so use this as quick math rather than an exact quote.
Quick Math #2: A $10,000 Higher Price Doesn’t Always Mean a $10,000 Higher Loan
Here’s where we make the shortcut even better.
Suppose you’re putting 5% down.
If the house costs $10,000 more, you aren’t borrowing the entire additional $10,000.
You’re putting down approximately:
5% × $10,000 = $500
And financing:
$9,500
Using our approximate $62-per-$10,000 shortcut:
$9,500 ÷ $10,000 × $62 ≈ $59 per month
So with 5% down, a $10,000 difference in purchase price might mean roughly $59 more per month in principal and interest, before considering changes in taxes, insurance or mortgage insurance.
That’s why I always tell buyers:
Don’t fall in love with—or reject—a house based solely on the purchase price.
Look at the payment.
Quick Math #3: Every 1% Down Equals $1,000 for Every $100,000 of Purchase Price
This one is incredibly easy.
For every $100,000 of home price, each 1% down equals:
$1,000
So on a $400,000 home:
| Down Payment | Cash Toward Down Payment |
|---|---|
| 3.5% | $14,000 |
| 5% | $20,000 |
| 10% | $40,000 |
| 15% | $60,000 |
| 20% | $80,000 |
Here’s the trick:
Take the purchase price and move the decimal.
For a $450,000 home:
1% = $4,500
Therefore:
5% = $22,500
10% = $45,000
20% = $90,000
You don’t have to reach for a calculator every time.
And don’t automatically assume you need 20% down. The appropriate down payment depends on your loan program, qualifications and financial strategy.
Start by seeing what you may qualify for using my Mortgage Qualification Calculator.
Quick Math #4: What Does a 0.25% Interest-Rate Difference Really Cost?
Interest-rate headlines can sound scary.
But translate the rate into dollars.
For example, moving from approximately 6.25% to 6.50% on a 30-year fixed loan increases principal and interest by about:
$16 per month for every $100,000 financed.
Approximately:
| Loan Amount | Approx. Difference From +0.25% |
|---|---|
| $100,000 | $16/month |
| $200,000 | $33/month |
| $300,000 | $49/month |
| $400,000 | $65/month |
| $500,000 | $82/month |
Again, rates and actual payments vary.
But now when someone says:
“Rates went up a quarter point!”
you can ask the much more useful question:
“What does that actually mean to MY payment?”
Sometimes the headline feels considerably larger than the actual monthly difference.
Quick Math #5: Property Taxes — Divide By 12
You find a house and see that the estimated annual property taxes are $6,000.
Quick math:
$6,000 ÷ 12 = $500 per month
That’s it.
Another useful shortcut:
If property taxes were approximately 1% of value annually, then every $100,000 of property value would represent approximately:
$1,000 per year
or:
$83 per month.
So:
$400,000 × 1% = $4,000 annually
$4,000 ÷ 12 ≈ $333 monthly
However, don’t use 1% as an assumption for every property. Actual taxes can vary significantly based on location, assessed value, exemptions and other factors.
The shortcut is simply:
Annual taxes ÷ 12 = monthly taxes.
Quick Math #6: Homeowners Insurance Works the Same Way
Let’s say you’re quoted:
$3,600 per year for homeowners insurance.
Divide by 12:
$3,600 ÷ 12 = $300 per month
A really easy insurance shortcut is:
Every $1,200 per year = $100 per month.
Therefore:
$2,400/year = $200/month
$3,600/year = $300/month
$4,800/year = $400/month
This becomes especially important when comparing homes because the mortgage isn’t the only part of the housing payment.
Your actual monthly housing expense may include principal, interest, taxes, homeowners insurance, mortgage insurance and HOA dues.
Quick Math #7: HOA Fees Are Dollar-for-Dollar Monthly
This one sounds obvious, but buyers sometimes underestimate it.
If House A has no HOA and Condo B has a:
$500 monthly HOA
that’s essentially another:
$500 per month of housing expense.
Compare that with our mortgage shortcut.
At approximately 6.25%, $500 of principal-and-interest payment is roughly equivalent to the P&I payment on about $81,000 of mortgage principal.
That does not mean a $500 HOA automatically reduces your buying power by exactly $81,000. Qualification also includes taxes, insurance, mortgage insurance and lending guidelines.
But it illustrates something important:
Don’t ignore the HOA when comparing properties.
A lower-priced condo with a large HOA payment may have a higher total monthly housing expense than a more expensive property with little or no HOA.
This is why the Affordability Calculator can be much more useful than looking at purchase price alone.
Quick Math #8: Every $100 of Monthly Debt Matters
Here’s one buyers often don’t think about.
Suppose you have:
$700 car payment.
That $700 doesn’t simply affect your checking account.
It also counts as monthly debt when you’re qualifying for a mortgage.
Using our approximate 6.25% mortgage example, every $100 of principal-and-interest payment represents roughly:
$16,200 of mortgage principal.
So $700 in monthly payment capacity is roughly the P&I equivalent of more than:
$113,000 of mortgage principal.
Do not interpret that to mean paying off a $700 car payment automatically increases your mortgage approval by $113,000.
It doesn’t work that way.
Taxes, insurance, mortgage insurance, interest rate, credit, down payment and underwriting requirements all affect qualification.
But it shows why I tell future homebuyers:
That $800 car payment may matter more to your homebuying plans than the $8 coffee.
If buying a home is a near-term goal, read my 3 Months Before Buying a Home: The Smart Buyer’s Game Plan.
Quick Math #9: Every $10,000 Extra Down Saves About $62 in Principal and Interest
Remember our first rule?
Approximately:
$10,000 financed = $62/month.
It also works backward.
If you put another $10,000 down and therefore finance $10,000 less, the principal-and-interest payment would decrease by approximately:
$62 per month
under our 6.25%, 30-year example.
Does that automatically mean you should put the extra $10,000 down?
Absolutely not.
That cash could potentially be more valuable to you as emergency reserves, money for repairs, moving expenses or other financial priorities.
And a larger down payment can sometimes affect mortgage insurance and loan pricing, which means the actual savings could be different.
The important thing is that now you can compare:
“Would I rather keep $10,000 in the bank or reduce my payment by approximately $62?”
That’s a financial decision you can actually evaluate.
Quick Math #10: Seller Contributions Add Up FAST
Let’s say you’re buying a:
$400,000 home.
If you negotiated a seller contribution of:
1% = $4,000
2% = $8,000
3% = $12,000
That can potentially make a significant difference in the amount of cash you need at closing when the contribution is permitted by the applicable loan program and transaction.
This is another reason buyers shouldn’t look only at:
“What’s the lowest price they’ll take?”
Sometimes the structure of the transaction can matter as much as the price.
For example, depending on your circumstances, you might prefer:
$400,000 with a $10,000 seller contribution
over:
$390,000 with no seller contribution
That depends entirely on your financing and available cash.
This is where working the numbers before writing the offer becomes extremely valuable.
Quick Math #11: One Mortgage Point = 1% of the Loan Amount
Here’s another easy one.
A mortgage “point” generally refers to:
1% of the loan amount.
Therefore:
$300,000 loan → 1 point = $3,000
$400,000 loan → 1 point = $4,000
$500,000 loan → 1 point = $5,000
Be careful about one common misconception:
One point does NOT necessarily lower your rate by 1%.
The amount by which discount points may reduce a rate depends on market pricing at that particular time.
But figuring out the cost of the point is easy.
Quick Math #12: Calculate the Break-Even on Paying Points
Suppose paying additional upfront costs would save you:
$100 per month
and those additional costs are:
$4,000.
Quick math:
$4,000 ÷ $100 = 40 months
That’s approximately:
3 years and 4 months
to recover the upfront cost through monthly savings.
If you think you’ll keep that mortgage substantially longer, it’s worth analyzing.
If you expect to sell or refinance much sooner, the calculation may look completely different.
This same basic formula can help when considering refinancing:
Upfront cost ÷ monthly savings = approximate break-even period.
You can explore scenarios using my Refinance Calculator and read When Does It Make Sense to Refinance? The Smart Homeowner’s Guide.
Quick Math #13: Calculate What You’re Paying in Rent Each Year
Take your rent and multiply it by 12.
If your rent is:
$2,500 per month
then:
$2,500 × 12 = $30,000 per year
Three years, assuming no rent increase:
$90,000
Five years:
$150,000
That doesn’t mean renting is “throwing money away.” Renting provides housing and can be the right decision depending on your circumstances.
But if you’re already spending $25,000, $30,000 or $40,000 every year for housing, it’s reasonable to find out what owning would look like.
Try my Rent vs. Buy Calculator.
Quick Math #14: Every $12,000 of Annual Income Equals $1,000 Gross Per Month
This is another incredibly useful shortcut.
Take annual income and divide it by 12.
So:
$60,000/year = $5,000/month
$72,000/year = $6,000/month
$84,000/year = $7,000/month
$96,000/year = $8,000/month
$108,000/year = $9,000/month
$120,000/year = $10,000/month
Mortgage qualification generally starts with gross monthly qualifying income, although what income can actually be used depends on documentation, stability, loan program and underwriting rules.
This calculation helps you understand where the numbers begin.
You can then plug them into the Mortgage Qualification Calculator.
The Quick-Math Cheat Sheet
If you remember nothing else from this article, remember these numbers:
| Quick Math | Rule of Thumb |
|---|---|
| Every $10,000 financed | ≈ $62/month P&I at 6.25% |
| Every $50,000 financed | ≈ $308/month P&I |
| Every $100,000 financed | ≈ $616/month P&I |
| +0.25% in rate | ≈ $16/month per $100K around 6.25%–6.50% |
| 1% down | $1,000 per $100K purchase price |
| $1,200/year insurance | $100/month |
| $1,200/year taxes | $100/month |
| $100 monthly HOA | $100 added monthly expense |
| $12,000 annual income | $1,000 gross monthly income |
| 1 mortgage point | 1% of loan amount |
| Rent | Monthly rent × 12 = annual rent |
| Break-even | Upfront cost ÷ monthly savings |
These aren’t meant to replace an actual mortgage analysis.
They’re meant to help you understand the numbers while you’re shopping.
Here’s Why This Matters When You’re Looking at Houses
Imagine you’re prequalified around $400,000 and find two houses.
House A costs:
$390,000
House B costs:
$410,000
You love House B significantly more.
A buyer who only looks at purchase price sees:
“$20,000 difference.”
Using quick math, assuming roughly the same financing structure, you might instead see:
“Approximately $120 more per month in principal and interest.”
Then you can ask yourself:
Would I pay about $4 per day for the location, extra bedroom, bigger backyard or better condition?
Because:
$120 ÷ 30 ≈ $4 per day.
Now you’re making a completely different decision.
That’s the power of understanding mortgage math.
Don’t Shop Only by Price. Shop by Payment.
A $400,000 home isn’t automatically affordable.
And a $425,000 home isn’t automatically unaffordable.
The complete picture depends on:
Your financing.
Your down payment.
Your interest rate.
Your property taxes.
Your insurance.
Your HOA.
Your other debts.
Your cash available.
And most importantly:
The monthly payment you’re comfortable carrying.
So the next time you’re scrolling through homes and thinking:
“That’s $20,000 over what I wanted to spend…”
don’t automatically close the listing.
Do the quick math.
Then do the real math.
Use my Mortgage Calculator, Affordability Calculator and Mortgage Qualification Calculator to see what the numbers actually look like.
And if you’d like help turning all those numbers into a strategy:
Book an Appointment
A smart homebuyer doesn’t just know the price of the house. A smart homebuyer understands what the numbers mean.
All calculations are illustrative approximations and are provided for educational purposes only. The approximately $62-per-$10,000 rule assumes a 30-year amortizing mortgage around 6.25% and represents principal and interest only. Actual interest rates, APRs, payments, taxes, insurance, mortgage insurance, HOA expenses, closing costs, lender credits, seller contributions and qualification requirements vary by borrower, property, market and loan program. This is not a commitment to lend or a rate quote.